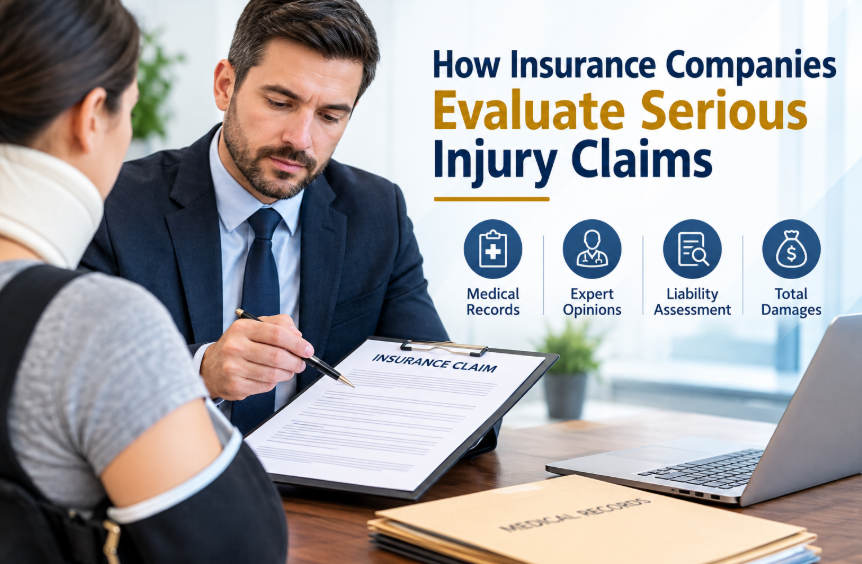

Understanding how insurance companies evaluate serious injury claims can help injured people approach the process with greater clarity and realistic expectations. Thomas Grier Injury & Car Accident Lawyers can assist claimants who need guidance while an insurer examines the circumstances and consequences of an injury. In Arizona, these evaluations can involve questions about liability, medical treatment, financial losses, and the coverage available under applicable policies.
A serious injury may affect far more than immediate medical needs, particularly when recovery takes time or changes a person’s ability to work and manage daily responsibilities. For Arizona residents pursuing compensation, understanding how insurers assess an injury’s overall impact can make it easier to recognize the importance of complete documentation, consistent information, and informed decisions throughout the claims process.
Accident Facts
Insurers first establish how the incident happened. Adjusters compare police reports, photographs, witness accounts, traffic footage, and vehicle damage. They may inspect weather, road conditions, and driver behavior. Liability can weaken if evidence shows shared fault, delayed reporting, or conflicting statements. A consistent timeline gives the reviewer a clear basis for deciding whether the policyholder caused the injury and whether compensation should follow under applicable policy coverage terms.
Medical Evidence
Medical proof is often the most important evidence. Reviewers examine emergency records, diagnostic images, physician notes, prescriptions, therapy plans, and specialist opinions. They compare early complaints with later findings. Treatment gaps may raise questions, especially if symptoms appear months after an accident. Continuous care, reasonable referrals, and clear diagnoses help connect the event with lasting physical or psychological effects that affect work, sleep, mobility, relationships, and ordinary household tasks.
Financial Losses
Financial losses receive separate review. Wage records, tax filings, employment contracts, business statements, and benefit summaries can show missed earnings. Serious cases may involve reduced future capacity, career changes, or permanent disability. Household services also carry value when an injured person cannot cook, clean, drive, or provide childcare. Reliable figures help separate proven losses from unsupported estimates or amounts without clear justification.
Policy Terms
Policy language sets another boundary. Adjusters check liability limits, exclusions, medical payment provisions, uninsured driver protection, and deadlines. Multiple policies may apply, including household, commercial, or employer coverage. Each contract can assign duties after an accident, such as prompt notice or cooperation. Missing a required step may create disputes, even where the underlying injury appears well documented, and the carrier may reserve rights while facts remain contested later.
Credibility Review
Credibility shapes settlement value. Insurers review prior injuries, earlier claims, social media posts, recorded statements, and public activity. A prior condition does not erase a new injury, but records must separate old symptoms from new impairment. Inconsistent descriptions can reduce trust. Accurate reporting, consistent appointments, and restrained online commentary protect the claimant’s position during negotiations and possible litigation if testimony later faces close comparison with written evidence.
Future Care
Future care receives attention in severe cases. Medical experts may estimate costs for surgery, rehabilitation, medication, equipment, counseling, and in-home assistance. The review also considers life expectancy, expected recovery, and probable complications. A credible forecast links each cost to a diagnosed condition. Unsupported predictions can weaken negotiations, while well-explained projections show why a present offer may fail to cover later needs through the claimant’s expected recovery period.
Settlement Offers
Settlement discussions reflect risk, proof, and projected expense. An initial offer often tests whether the claimant knows the file’s value. Reviewers may cite disputed fault, limited treatment, prior conditions, or policy restrictions. A measured response identifies each weakness, supplies stronger records, and calculates damages. Negotiation usually improves when evidence answers objections before they become fixed positions or when it encourages a fairer assessment of the available recovery for both sides.
Litigation Preparation
Litigation readiness can affect an insurer’s response. Counsel may preserve evidence, question witnesses, consult medical specialists, and prepare filings before talks end. This preparation signals that delay will not erase the claim. Court rules also impose deadlines, disclosure duties, and proof standards. Even if settlement remains likely, organized preparation protects options and supports decisions based on documented facts rather than pressure, speculation, or incomplete records during review.
Building a Stronger Serious Injury Claim
Serious injury valuation depends on proof that connects responsibility, medical harm, financial loss, and future needs. Insurance reviewers search for gaps, contradictions, unsupported forecasts, and policy barriers. Claimants can strengthen a file through prompt care, accurate records, consistent communication, and realistic damage calculations. Legal guidance may help protect evidence and respond to low offers. A careful presentation gives each loss a reason, amount, and connection to the accident without overstating what records can fully prove.